October 29, 2026 — Analyze core shifts in alternative investments, from PGIM and LGT’s $680M continuation vehicle to BlackRock’s hedge fund outlook and private credit growth.
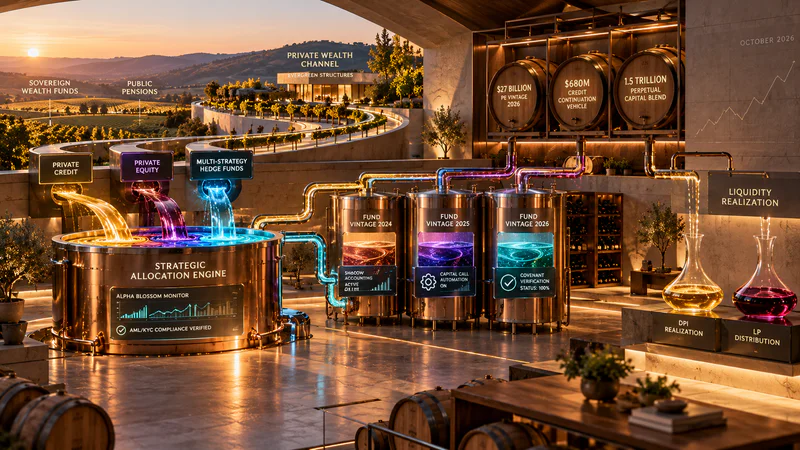
The alternative investment landscape is undergoing significant operational and structural realignments. From multi-billion-dollar continuation vehicles in private credit to record-breaking private equity fund closes and AI-driven quantitative strategies in hedge funds, institutional allocators are rethinking their portfolio construction frameworks.
As market concentration among mega-cap fund managers intensifies, understanding these shifts across private credit secondaries, venture capital, and multi-strategy hedge funds is critical for General Partners (GPs) and Limited Partners (LPs) aiming to generate sustainable alpha.
Key Takeaways
Private Credit Continuation Acceleration: PGIM and LGT Capital Partners co-led a $680 million private credit continuation vehicle for Tree Line Capital Partners, reflecting the expansion of liquidity options in direct lending.
Perpetual Capital Scale: The top five listed private markets managers control $1.5 trillion in perpetual capital, driving expansion into wealth management and retail channels.
Hedge Fund AI Integration: BlackRock’s latest Hedge Fund Outlook highlights how systematic, AI-driven models are capturing cross-asset dispersion and navigating ongoing inflation shocks.
Capital Concentration in Venture: Established venture capital firms captured 88% of LP commitments in early 2026, forcing emerging managers to demonstrate clear operational value-add.
1. Private Credit: Continuation Vehicles and Secondaries Scale
The private credit sector continues to mature through structural innovations designed to offer LP liquidity without forcing early loan liquidations. A key milestone is the closure of a $680 million private credit continuation vehicle co-led by PGIM and LGT Capital Partners alongside Tree Line Capital Partners.
This transaction highlights several broader operational trends in private debt:
Expanding Credit Secondaries: Evergreen and secondary credit vehicles now provide institutional liquidity solutions across direct lending and asset-backed debt.
Institutional Borrower Continuity: Continuation structures allow high-performing middle-market lenders to maintain key borrower relationships beyond traditional fund life cycles.
Cross-Asset Entry: Multi-strategy hedge funds like Millennium Management and Point72 are increasingly entering opportunistic credit, compressing spreads in direct corporate debt.
2. Private Equity and Venture: Navigation Concentration Risks
Advent International’s GPE XI fund close at nearly $27 billion highlights the persistent flight to quality among institutional allocators seeking established distribution records. However, capital concentration presents distinct challenges across the deployment spectrum:
Buyout Realization Pressure: LPs are demanding clear evidence of cash-on-cash distributions (DPI) before committing capital to new vintages, prompting GPs to leverage continuation funds and strategic secondary sales.
Venture Capital Flight to Quality: With established VC firms capturing 88% of LP commitments, emerging managers are adopting specialized, sector-focused strategies in software, climate tech, and AI infrastructure to differentiate themselves.
Mid-Market Carve-Outs: Major sponsors are pivoting toward mid-market corporate carve-outs to acquire cash-generative businesses at disciplined entry multiples.
3. Hedge Funds: AI Alpha and Macro Dispersion
In its Hedge Fund Outlook published on October 27, 2026, BlackRock emphasized that macro volatility, geopolitical fragmentation, and rapid technological disruption are creating historically wide performance dispersion across global equity and credit markets.
To capitalize on these macro shifts, quantitative and multi-strategy hedge funds are advancing their technology stacks:
AI-Driven Pattern Recognition: Managers utilize large language models (LLMs) and advanced machine learning algorithms to process complex macroeconomic data and identify short-term mispricings.
Event-Driven Catalyst Trading: A renewed corporate change supercycle—driven by corporate restructurings, M&A, and technological spin-offs—is offering fertile ground for event-driven strategies.
Volatility as a Strategic Tool: Rather than hedging against market swings, multi-strategy platforms treat macro volatility as an active driver of non-correlated alpha.
4. Democratization and Wealth Management Channels
The democratization of alternative asset classes continues to transform how fund managers scale AUM. Major asset managers—including Apollo, Ares, Blackstone, Carlyle, and KKR—are expanding their wealth management channels.
Evergreen, semi-liquid fund vehicles (such as interval funds and non-traded BDCs) allow high-net-worth investors and wealth advisors to access institutional-grade private credit, private equity, and real estate strategies with lower minimums and periodic liquidity options.
Conclusion: Operational Precision in Modern Alternatives
The alternative investment landscape demands a balance between strategic deal-making and modernized operational infrastructure. Whether managing complex continuation vehicles, automating LP onboarding for wealth channels, or ensuring compliance across multi-entity fund structures, GPs must replace manual legacy back-office workflows with automated platforms.
Ultimately, the competitive divide in 2026 will not be drawn solely by asset class selection, but by operational execution speed and LP transparency. Fund managers who leverage unified digital architecture to connect portfolio accounting, compliance monitoring, and automated investor portals will eliminate back-office friction, lower overhead costs, and position themselves to seamlessly capture incoming institutional and retail wealth capital at scale.
Learn how Ashta.ai unifies multi-entity fund accounting, automated LP onboarding, and compliance governance into a single connected platform built for modern private market managers.
In summary, as private markets expand into AI infrastructure, asset-backed credit, and evergreen fund structures, success in late 2026 will be defined by operational agility and precision. General Partners who replace manual legacy workflows with unified, automated operating infrastructure will be best positioned to mitigate cyber risks, ensure compliance, and deliver seamless LP experiences at scale.