November 3, 2026 — Analyze how private equity CFOs use shadow accounting and automated valuation governance to satisfy LP and SEC scrutiny. Book a demo: https://calendly.com/khushboojha/
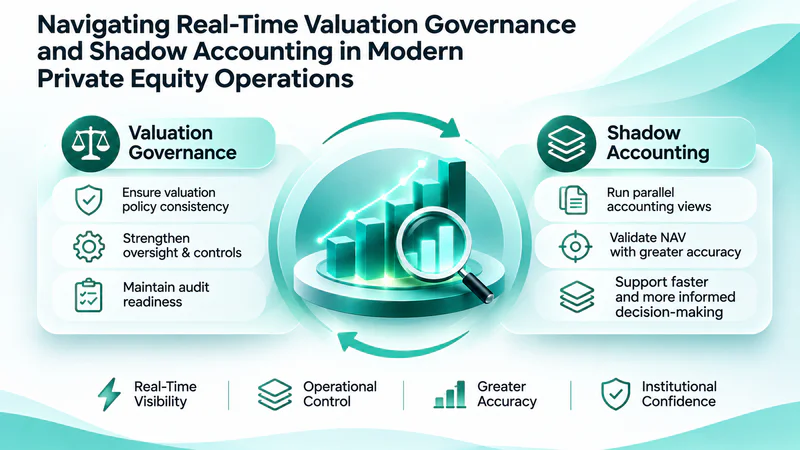
As institutional allocators demand total transparency and regulatory bodies intensify scrutiny around illiquid asset markdowns, the traditional quarterly fund accounting cycle is no longer sufficient. Private equity CFOs and Chief Compliance Officers (CCOs) face a dual operational mandate: maintaining real-time portfolio valuation integrity while independently verifying third-party fund administrator outputs.
Historically, fund managers relied on manual shadow accounting spreadsheets to mirror administrator ledgers and track complex valuation waterfalls. However, as private market portfolios expand into co-investments, continuation vehicles, and hybrid credit-equity structures, offline shadow books create dangerous operational friction.
To eliminate valuation discrepancies, satisfy stringent SEC examination guidelines, and streamline LP reporting, forward-thinking General Partners (GPs) are adopting automated valuation governance engines and integrated shadow accounting platforms.
Key Takeaways
The Fall of Spreadsheet Shadow Books: Manual shadow accounting models are error-prone and fail to provide the real-time valuation line-of-sight required by institutional LPs in late 2026.
Automated Valuation Governance: Programmatic rules enforce valuation methodologies, markdowns, and ASC 820 fair value inputs directly within the core general ledger.
Streamlined Admin Reconciliation: Connected fund operating systems automatically reconcile internal shadow ledgers against fund administrator statements, flagging exceptions instantaneously.
Audit-Ready Valuation Vault: Storing model inputs, board approval timestamps, and valuation committee overrides creates an immutable trail for SEC sweep exams.
1. Deconstructing the Operational Drag of Manual Shadow Accounting
Managing shadow accounting across multi-tier parallel vehicles involves verifying complex capital flows, waterfall splits, and portfolio company valuations. When fund finance teams rely on offline spreadsheets, critical operational bottlenecks emerge across key workflow areas:
Admin Reconciliation: Shifting from slow manual spreadsheet matching to real-time, API-driven automated reconciliation.
Fair Value Input Tracking (ASC 820): Replacing unverified valuation notes with an immutable, programmatic audit trail.
Waterfall & Carry Recalculation: Transitioning from fragile formula modeling to an automated, multi-feeder engine.
Exception Management: Moving away from reactive error detection to instant, automated discrepancy alerts.
Valuation Committee Workflow: Replacing informal email chains with centralized digital approval governance.
Primary Risk Vectors:
Reconciliation Lag: Manual matching of monthly administrator NAV reports against internal spreadsheets can take weeks, leaving CFOs blind to cash or position discrepancies during active fundraising windows.
Valuation Input Inconsistencies: Applying different discount rates or EBITDA multiples across parallel vehicles leads to misaligned NAV calculations, triggering regulatory red flags and LP disputes.
Audit Fatigue: Gathering historical valuation committee notes, deal team memo versions, and model adjustments for annual audits or SEC exams consumes hundreds of hours of back-office time.2. Regulatory Enforcement: SEC Scrutiny on Private Market Valuations
Regulatory priorities in late 2026 place heavy emphasis on how private equity and credit managers value hard-to-value assets during periods of market volatility. Regulators are actively inspecting:
Valuation Policy Deviations: Assessing whether GPs strictly adhere to documented valuation policies or apply ad-hoc overrides to avoid asset write-downs.
Conflicts of Interest in Carry Calculations: Ensuring that unrealized asset marks used to calculate interim performance fees or carried interest distributions are backed by verifiable market data.
Co-Investor Parity: Verifying that co-investment vehicles and flagship funds apply identical fair value marks to shared portfolio holdings.
3. How Connected Infrastructure Automates Shadow Accounting
Modern private market platforms unify multi-entity fund accounting, portfolio tracking, and valuation governance into a single connected platform, transforming shadow accounting from a defensive chore into a strategic advantage.
Automated Admin Data Ingestion
Connected platforms ingest raw general ledger feeds and transaction logs directly from third-party fund administrators via secure APIs. The system automatically reconciles cash balances, investor call ledgers, and portfolio holdings, flagging line-item variances instantly.
Programmatic Valuation Governance
Valuation models are embedded directly into the platform workflow. As deal teams submit updated financial inputs, discount rates, or comparable company multiples, the engine recalculates asset values across all holding entities, enforcing consistent ASC 820 classification protocols.
Centralized Approval Workflows
Valuation committee members review, challenge, and sign off on asset marks within an encrypted compliance portal. Every adjustment, commentary, and supporting document is automatically logged into an immutable audit trail.
Conclusion: Achieving Institutional Precision in Private Market Operations
Operational agility and transparent governance are vital for building institutional LP trust. General Partners can no longer rely on fragile, manual spreadsheets to verify third-party administrator calculations or defend asset valuations. By deploying automated shadow accounting and valuation governance infrastructure, CFOs ensure absolute ledger accuracy, mitigate regulatory exposure, and position their firm to scale seamlessly.
Learn how Ashta.ai unifies multi-entity fund accounting, automated LP onboarding, and compliance governance into a single connected platform built for modern private market managers.
In summary, as private markets expand into AI infrastructure, asset-backed credit, and evergreen fund structures, success in late 2026 will be defined by operational agility and precision. General Partners who replace manual legacy workflows with unified, automated operating infrastructure will be best positioned to mitigate cyber risks, ensure compliance, and deliver seamless LP experiences at scale.