October 27, 2026 — Discover key trends shaping private markets, from Blackstone’s $330B wealth milestone to ILPA continuation vehicle guidance and hedge fund credit entry.
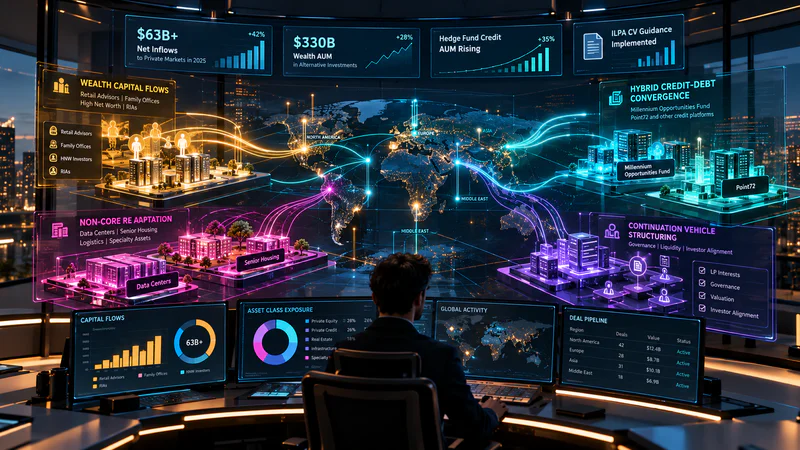
October 27, 2026 — The private markets industry is undergoing a profound transformation. From record-breaking wealth management milestones to shifting real estate dynamics, the convergence of hedge funds and private credit, and new governance frameworks for continuation vehicles, recent developments highlight an industry in rapid motion.
General Partners (GPs), institutional allocators, and wealth management platforms must adapt to a landscape where traditional asset class boundaries are blurring, exit environments remain complex, and individual investor capital is reshaping fundraising dynamics.
Key Takeaways
Democratization at Scale: Blackstone’s private wealth assets under management (AUM) reached a record $330 billion in Q3 2026, driven by nearly $9 billion in quarterly individual investor inflows across retail-focused vehicles.
Institutional Real Estate Pivot: While overall closed-end real estate fundraising remains subdued, 70% of allocator intentions tilted toward non-core strategies like value-add, opportunistic, senior housing, and AI-driven data centers.
Hedge Fund Entry into Private Credit: Multi-strategy giants including Millennium Management and Point72 are entering asset-backed and opportunistic credit, accelerating competition in a $1.5 trillion North American market.
ILPA Governance on Continuation Vehicles: ILPA finalized principles-based guidance for continuation vehicles (CVs)—which now represent roughly one-fifth of private equity distributions—emphasizing valuation transparency and GP-LP alignment.
1. Blackstone’s Record Achievements in Private Wealth
Blackstone has demonstrated the immense scale of the private wealth sector. The firm's AUM from individual investors reached a record $330 billion in Q3 2026, marking a 15% increase year-over-year. In a single quarter, the firm attracted nearly $9 billion from individual investors, illustrating the accelerating pace of private market democratization.
Leading this influx was BXPE, Blackstone's private equity program for individuals, which raised $2.9 billion in Q3. BXINFRA brought in $1.1 billion, while the launch of multi-strategy international vehicles expanded reach across global markets.
This trend extends across the entire alternative investment landscape. Fund managers are actively expanding wealth channel architectures—such as semi-liquid structures, model portfolios, and evergreen funds—to capture individual investor capital that was historically locked out of institutional private equity.
2. Real Estate: Subdued Fundraising and Non-Core Shifts
The real estate sector presents a nuanced narrative in late 2026. Closed-end real estate funds raised $81.7 billion in H1 2026 across just 95 final closes, representing one of the lowest half-year totals in over a decade. Macroeconomic volatility and capital concentration remain prevalent, with the top 10 funds securing nearly half of all capital raised.
However, beneath top-line fundraising figures, allocators are repositioning capital:
Non-Core Demand Dominance: Value-add, opportunistic, and specialized property types represented 70% of institutional allocator intentions in H1 2026. Major public pension systems are actively doubling non-core allocations to capture higher risk-adjusted yields.
Data Centers and Senior Housing: AI infrastructure needs continue to drive capital toward data center real estate, while demographic shifts sustain demand for specialized senior housing facilities.
Dominance of Private REITs: Private wealth channels continue to provide essential liquidity for real estate sponsors, with large non-traded private REITs capturing the majority of wealth-allocated net asset value.
3. Private Credit: Hedge Fund Giants Enter the Arena
The private credit market is experiencing a structural shift as major multi-strategy hedge funds expand into private debt. Millennium Management is raising $5 billion for an evergreen vehicle focused on asset-backed credit, real assets, and opportunistic corporate debt.
This entry alongside firms like Point72 and Third Point is redefining market dynamics across North America’s $1.5 trillion private credit sector:
Increased Capital Competition: Spreads have compressed as mega-cap hedge funds bring vast analytical capabilities and flexible capital into asset-backed and hybrid debt transactions.
European Market Expansion: Managers are expanding into European credit markets, which captured record inflows as sponsors seek yield opportunities beyond crowded domestic markets.
Emerging Hybrid Strategies: Emerging managers are scaling niche strategies, including fund financing and hybrid capital solutions, offering lower correlation to public credit and attractive illiquidity premiums.
4. Private Equity Governance and Continuation Vehicles
As private equity matures, generating excess returns requires disciplined asset selection, operational value creation, and strategic technology integration rather than relying solely on multiple expansion or cheap leverage.
A key governance milestone this week was the release of finalized continuation vehicle (CV) guidance by the Institutional Limited Partners Association (ILPA). Emphasizing a principles-based approach over rigid rules, the guidance focuses on:
Valuation Transparency: Ensuring independent fairness opinions and transparent pricing benchmarks before assets are transferred.
LP Option Clarity: Providing LPs with clear, conflict-free choices to roll their equity or cash out at fair market value.
Fee Alignment: Aligning GP crystallizations and roll terms to prevent unearned carried interest payouts.
With continuation vehicles accounting for approximately 20% of total LP distributions in current market conditions, clear governance standards ensure CVs remain a viable structural tool for managing extended holding periods.
Conclusion: Strategic Execution in a Converging Market
The private markets landscape in late 2026 is defined by structural convergence. Blackstone’s wealth milestones confirm that individual investor capital is now a permanent pillar of private fund growth. Simultaneously, real estate strategies are pivoting toward non-core opportunities, hedge funds are entering private credit, and ILPA guidance has formalized continuation vehicles within mainstream fund operations.
General Partners who replace static legacy operations with connected, automated fund infrastructure will be best positioned to scale wealth distribution, execute complex multi-entity allocations, and maintain regulatory compliance across every fund vintage.
Learn how Ashta.ai unifies LP onboarding, multi-entity fund accounting, and compliance governance into a single connected platform built for modern private market managers.
In summary, as private markets expand into AI infrastructure, asset-backed credit, and evergreen fund structures, success in late 2026 will be defined by operational agility and precision. General Partners who replace manual legacy workflows with unified, automated operating infrastructure will be best positioned to mitigate cyber risks, ensure compliance, and deliver seamless LP experiences at scale.